In the work we do as advisors, we often talk with client families about evaluating decisions and measuring success. What were our expectations? Did our choice produce the intended results?
In the context of making long-term portfolio investments, there are a few ways we can gauge our success:
There’s the absolute measure: Did the investment grow or decline in value?
There’s the relative measure: Did the investment do better or worse than a comparable asset?
There’s the goals-based measure: Did the investment produce enough income and growth to meet cash flow needs?
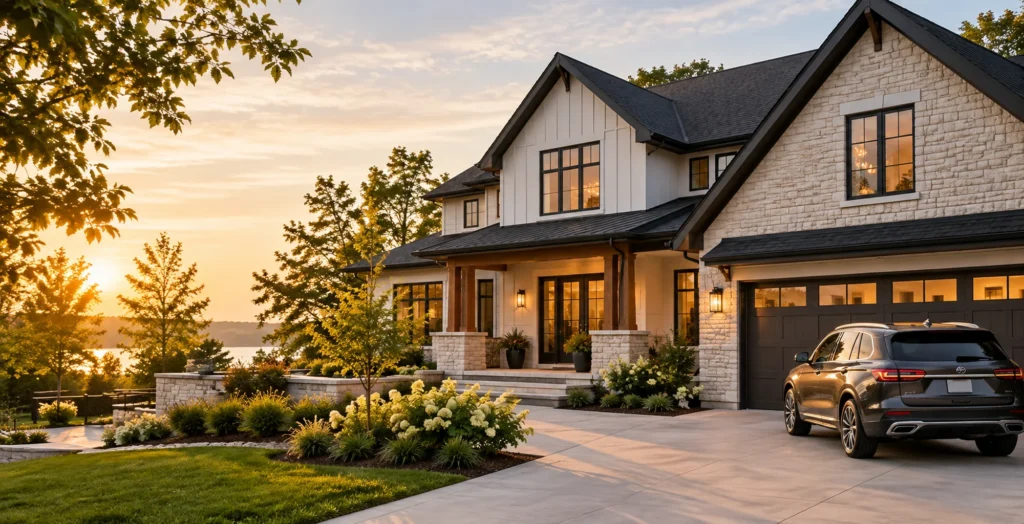
These measures work well for stock and bond investments, whether they’re mutual funds or individual securities. However, they don’t work as well for a special type of investment that client families often dream of pursuing, a second home. We need a different approach to evaluate an investment of the heart, a different kind of “bond” investment. An investment in joy requires a unique type of cost-benefit analysis.
Costs are easy to quantify.
The costs of making a second home investment are straightforward and relatively easy for families to quantify. There are dollar amounts built into the purchase price of the home: a monthly mortgage payment, the property taxes and homeowners’ insurance premium, the homeowners’ association dues, utilities, the regular maintenance, the unexpected repairs or replacements, and the furniture and home furnishings.
Other financial decisions a family may consider in making a second home investment. For instance, should they pay cash or take out a mortgage? Do they want to list the home for rent when the family is not using it? And, how should the home be titled for estate planning purposes? As advisors, we often help our client families navigate these decisions.
Benefits are more qualitative.
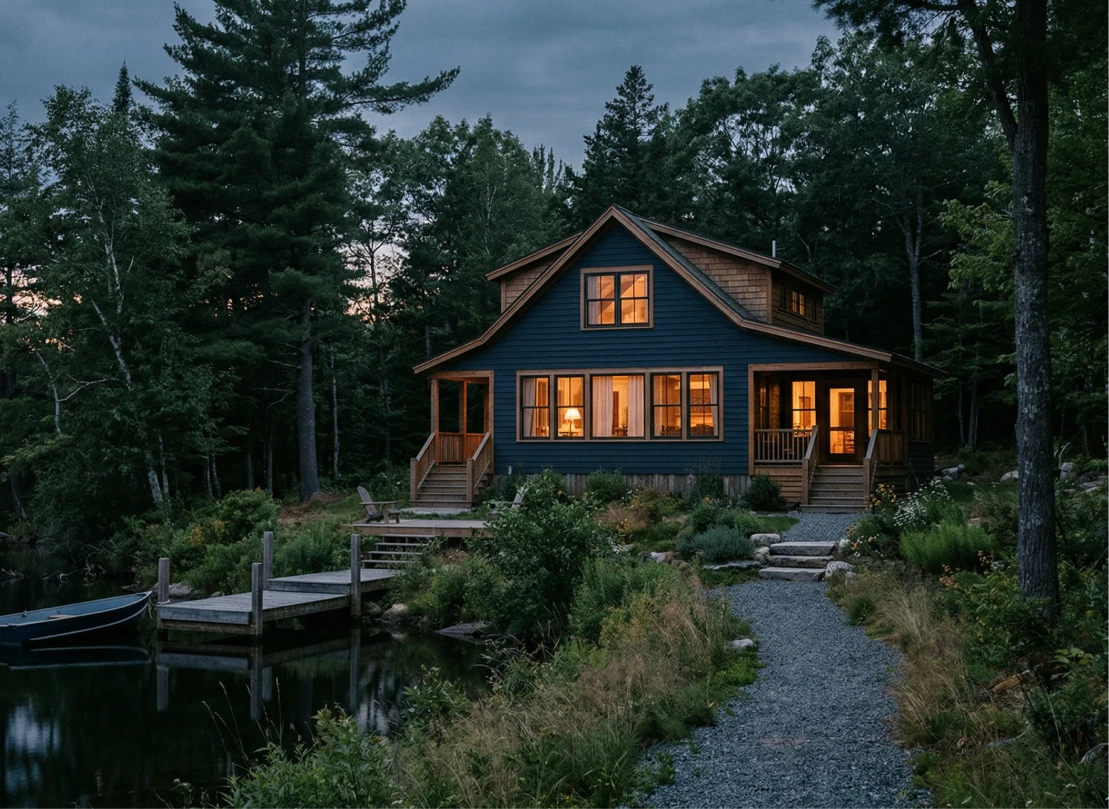
Unlike costs, the benefits of making a second home investment are priceless, often non-financial, and much more difficult to measure. There isn’t a simple formula to calculate the value of creating a generational retreat where a family can make years of memories together. The joy of hosting holiday gatherings, milestone celebrations, or family reunions at a beloved family haven simply can’t be reduced to a dollar amount.
Like all sound investments, a family makes a second home investment with the hope that its emotional value compounds over time. The second home is a special place where grandparents can spend quality time with their grandchildren before the busy activity calendar takes over the family schedule. It’s a place where cousins and siblings can ditch the devices and have a few adventures outside. Someday, the youngest in the family will bring their own children to this special place where they had so many happy memories in their youth. The true returns on a second home investment can’t be measured in dollars and cents, but rather in the strength of the family bonds that it helps create.
Deciding to buy a different kind of “bond” investment.
Making a second home purchase decision calls for a special set of evaluation criteria. At Foster Group, we understand that purchasing a second home is more than adding a real estate asset to the balance sheet. It’s an investment in family bonds that may appreciate in value across generations. If you are considering a second home investment, remember to consider the returns of the heart in addition to the financial costs. Connect with us today, and let’s talk about a different kind of “bonds.” Foster Group takes the time to truly know our clients—not just their financial goals, but what’s in their hearts.