Every year, December 31 seems to sneak up on us. Suddenly, we’re surrounded by checklists from newspapers, magazines, and well-meaning friends asking, “Have you done this yet?”, all with that looming year-end deadline.
And let’s be honest: no one enjoys scrambling to make last-minute financial moves before the clock strikes midnight on New Year’s Eve. So instead of rushing, let’s take a breath and walk through a few smart strategies you could consider before the year wraps up, including ways to reduce taxes, enhance your charitable giving, and even support your family in meaningful, tax-efficient ways.
To help unpack these ideas, we turned to Caleb Brown, Lead Advisor at Foster Group, who helps individuals and families make wise financial choices, often volunteering his time to help those who can’t afford professional tax help. Caleb has a gift for making complex tax rules and financial strategies easy to understand. In his recent video, 2025 Year-End Tax Strategies, he shared several ideas to help you finish the year strong. We’ve outlined those ideas below.
Understanding Standard vs. Itemized Deductions
First, let’s start with a foundational concept, the difference between standard and itemized deductions.
Most taxpayers take the standard deduction, a flat amount that simplifies filing. For 2025, it’s a little over $30,000 for married couples filing jointly and will increase to $32,200 in 2026. But if your eligible expenses (like medical costs, mortgage interest, state and local taxes, and charitable giving) add up to more than that amount, you can choose to itemize and potentially get a bigger deduction.
Another consideration is the state and local tax deduction (SALT) limit, which increased to $40,000 starting this tax year, 2025, following passage of the One Big Beautiful Bill Act. This is another potentially helpful adjustment for those with higher incomes or significant property or state taxes.
The key takeaway? You get to choose which results are a better outcome for you. Knowing the difference and tracking your potential itemized expenses can help you make the most of your tax situation.
Charitable Giving: Timing Matters
Charitable giving is one of the most powerful and fulfilling ways to reduce your taxable income. While the new tax bill will change some rules starting in 2026, it’s worth knowing how this year’s giving can still make a big difference.
For example, in 2025, there’s no “floor” on charitable deductions, meaning all of your giving counts toward itemized deductions. That will change next year, so 2025 could be a great year to lean into generosity. In 2026, there will be a floor on the deduction for charitable gifts of 0.5% of adjusted gross income. And for those taxpayers in the 37% federal income tax bracket, the tax break will be capped at 35%, starting next year.
Donor-Advised Funds: A Triple Win
One of Caleb’s favorite tools for charitable giving is the Donor-Advised Fund (DAF). Think of it as your personal giving account, or an account that you contribute to now and receive an immediate tax deduction but distribute to your favorite charities later.
Here’s how it works (for illustrative purposes only): Instead of donating cash, you can contribute appreciated investments, such as a stock you bought years ago for $10,000 that’s now worth $20,000. By gifting the stock directly into a DAF:
- You avoid paying capital gains taxes on that $10,000 gain.
- You get a tax deduction for the full $20,000 value.
- And your charity receives the full $20,000.
That’s what we call a win-win-win for you, your taxes, and the charity.
Giving Directly from an IRA: QCDs
If you’re over 70½ years old, another incredibly tax-efficient way to give is through a Qualified Charitable Distribution (QCD). This allows you to donate directly from your IRA to a qualified charity up to the annual limit of $108,000 for 2025 and increasing to $115,000 for 2026. The beauty of a QCD is that the money never counts as taxable income, even though it could satisfy your required minimum distribution (RMD). By doing this, you can lower your taxable income, provide support for causes you care about, and potentially reduce your Medicare premiums and tax exposure on Social Security income. As Caleb puts it, “It’s one of the smartest giving strategies for retirees, and the charities get the full benefit.”
Don’t Forget About Family Giving
Charitable giving isn’t the only form of generosity to consider at year-end. Many people use this season to help family members financially, and the IRS gives you a simple, tax-friendly way to do it. In 2025, you can give up to $19,000 per person, $38,000 for married couples, without any tax reporting. That amount is called the annual exclusion gift limit, and it’s a simple way to share your resources with children, grandchildren, or anyone important to you whether to help with a home, education, or just to bless their lives. You can even gift appreciated securities to family members who may be in lower tax brackets, helping them out while reducing your own potential capital gains exposure. A thoughtful strategy like that can turn a tax burden into an opportunity.
529 Plans and Education Legacy
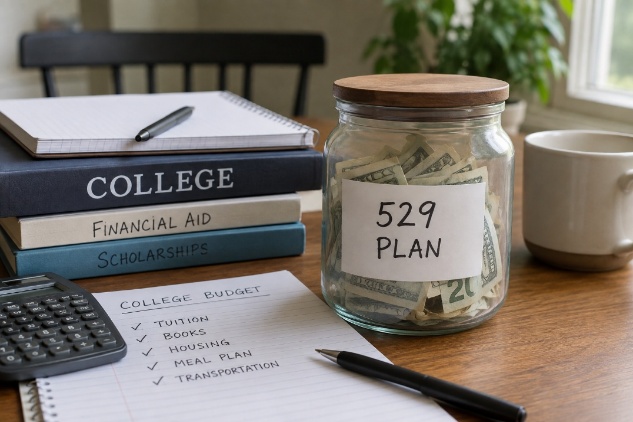
If you’re thinking about helping with education costs, a 529 college savings plan is a powerful tool. These plans allow contributions to grow tax-free, and withdrawals for qualified education expenses like tuition, books, or even tutoring are also tax-free.
In many states, contributions even come with a state tax deduction. If your child or grandchild doesn’t use all the funds, you can transfer the remaining balance to another family member or, under new rules, roll some of it, up to certain limits, into a Roth IRA for their future retirement. That’s long-term planning with real multigenerational impact.
Retirement Contributions and Roth Conversions
If you’re still working, now’s the time to check your 401(k) contributions. For 2025, you can contribute up to $23,500, with additional catch-up contributions totaling $31,000 for those over 50. In addition, those between the ages of 60-63 are allowed a special catch-up that they can contribute, a total of $34,750 to a 401(k) this year.
If you’re nearing or in retirement, consider whether a Roth conversion makes sense. This involves moving money from a pre-tax IRA to a Roth IRA and paying taxes now at potentially lower rates so that future growth and withdrawals are tax-free. It’s a great strategy to consider in the years between retirement and when required minimum distributions begin, a period often described as a “valley” of lower taxable income. Paying some tax now could mean paying far less later.
Start the Conversation Early
Whether it’s maximizing deductions, giving generously, or planning for your family’s future, the best time to align your money with your values is now. And that’s a great way to end any year. What does it mean to be truly cared for? It means we understand your passions and use proven methods to help you reach your goals.