New 529 Plan Rules Are Changing the College Savings Conversation
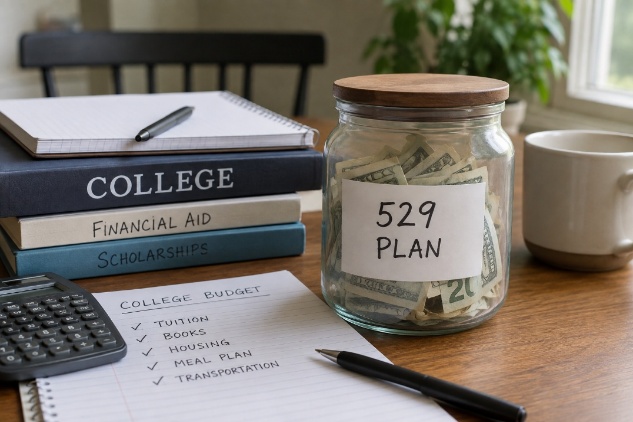
A few months ago, a friend of ours called me with a familiar worry. Her daughter had just landed a generous merit scholarship. That should have been a cause for pure celebration. Instead, she found herself wondering about the 529 plan she had funded so carefully since her daughter was in kindergarten. What happens to unused 529 plan funds if they aren’t needed for college expenses?
It is a common question we hear, and it always comes from a good place. People save diligently, then wonder if they saved too much or over-engineered their plans.
The encouraging answer is that this concern is much less of a risk today. Over the past few years, 529 accounts have quietly become one of the more versatile tools in long-term planning, covering not just college but multiple stages of life. Let’s walk through what’s new and how to use these accounts more intentionally.
From “College-Only” to Lifecycle Tool
Originally, 529 plans were tightly tied to higher education. But legislative changes, including the SECURE 2.0 Act of 20221 and the One Big Beautiful Bill Act signed in July 20252, have broadened what counts as a qualified expense.
The result is an account that now supports different educational phases and offers a real backstop if funds go unused. That flexibility is what makes it worth revisiting, even for families who already have accounts in place and think the heavy lifting is done.
New 529 Plan Rules Families May Be Overlooking
Can You Use a 529 Plan for K-12 Tuition?
Since 2018, families could use 529 funds for up to $10,000 per year in K–12 tuition.3 As of January 1, 2026, that annual limit doubled to $20,000 per student under the One Big Beautiful Bill Act.2 And it is not just for tuition anymore. Qualifying K–12 expenses now include curriculum materials, tutoring, standardized test fees, and educational therapies for students with learning differences.2 For families balancing private school costs alongside test prep, that adds up quickly.
One important nuance: These expanded benefits apply at the federal level, but state tax treatment varies. Some states have not updated their own rules to match the new federal limits, meaning a withdrawal that is federally tax-free could still trigger state income tax. A quick review of your state’s rules can help avoid any surprises.
Quick reminders on K–12 use:
- The $20,000 limit is annual, not lifetime, and applies per beneficiary.
- The limit applies across all 529 accounts for the same beneficiary combined.
- State conformity may vary, so confirm your state’s treatment before withdrawing.
A New Escape Hatch: How Do Roth IRA Rollovers Work?
This is the update that has generated the most relief. Since January 1, 2024, unused 529 funds can be rolled into a Roth IRA for the same beneficiary, free of the taxes or 10 percent penalty that used to apply to non-qualified withdrawals.1,4 In practice, this provides another option if a child does not use all the funds in a 529 plan. A portion can be redirected into long-term retirement savings with potentially decades of tax-free growth ahead.
Current rollover rules (SECURE 2.0 Act, 2022):1
- The lifetime rollover limit is $35,000 per beneficiary.
- The 529 must have been open for at least 15 years.
- Contributions from the last 5 years are excluded.
- Annual Roth IRA contribution limits still apply ($7,500 in 2026; $8,600 if age 50+).
- The beneficiary must have earned income equal to or greater than the rollover amount.
One detail that catches almost everyone off guard: The rollover bypasses the usual Roth IRA income limits. High earners who are normally ineligible to contribute directly to a Roth could consider this path.5
Pro Tip: Don’t Close the 529 Account Early
This one is simple and often missed.
Because the Roth rollover depends on a 15-year clock, closing a 529 too early can permanently limit future flexibility. The timing is based on when the account was first established, not when contributions were made to it.1,4 So even if a child has finished school, received a scholarship, or simply did not use all the funds, keeping the account open preserves your options. It maintains that 15-year clock, allows for future beneficiary changes, and keeps the door open for repurposing.
One caveat: It’s still unclear, but changing the beneficiary to a different family member may restart the 15-year clock for that new beneficiary. This move deserves a conversation rather than a reflexive decision.4,5 Sometimes the best move is simply not doing anything until all rules are clarified. Consult your financial professional regarding your individual circumstances.
Using a 529 Plan Across the Lifecycle
For many families, this changes the conversation from “Should we use a 529?” to “How do we use it strategically across time?” Here is one way to think about it by stage:
| Stage | Focus | Key Move |
|---|---|---|
| Early (young kids) | Long-term growth | Maximize contributions; let it compound |
| Mid (middle/high school) | Evaluate K–12 use | Tap up to $20K/year for qualifying expenses |
| Late (college and beyond) | Reassess balances | Sibling transfer, grad school, or Roth rollover |
For illustrative purposes only.
The key is intentionality, not rigid planning. 529 plans no longer require perfect foresight. Instead, they reward thoughtful, adaptable use over time.
Why Overfunding a 529 Plan Is Less Risky Than It Used to Be
That is what has changed with 529 plans. The families who get the most out of these accounts are not the ones chasing every new provision the moment it passes. They are the ones who open accounts early, keep good records, and revisit the plan periodically as life changes.
If you have a 529 account sitting somewhere in your financial picture, whether overfunded, underfunded, or just sitting quietly, it may be worth a conversation with a Foster Group advisor about what these new rules mean for your family’s specific situation and timeline. What does it mean to be truly cared for? It means we understand your passions and use proven methods to help you reach your goals.
Sources
2.One Big Beautiful Bill Act, Pub. L. No. 119-21, Secs. 110110–110111 (July 4, 2025)
3.26 U.S.C. § 529, Qualified Tuition Programs, Internal Revenue Code
4.IRS Topic No. 313, Qualified Tuition Programs (QTPs)
5.IRS Publication 590-A, Contributions to Individual Retirement Arrangements (IRAs) (2025)