While preparing for an upcoming webinar on generational wealth, I had the opportunity to work with Brittany Heard, Lead Advisor at Foster Group.
Her insights offered a fresh perspective on what it truly means to pass money, and meaning, from one generation to the next. While it’s easy to assume these discussions are mostly about investments, taxes, and accounts, the reality is much more personal. At its core, wealth transfer is about communication, values, and the everyday habits that shape how the next generation thinks about money.
Following our discussion, three insights stood out in a way that felt both practical and deeply relevant for families at any stage.
Thoughtful Communication Lays the Foundation for Passing on Wealth.
One of the clearest themes from our conversation was how much expectations have shifted over time. In the past, it wasn’t unusual for families to learn about inheritances only after a loved one had passed. Today, that kind of silence can lead to confusion and even lasting conflict.
The issue isn’t usually the money; it’s the lack of clarity around it. When families don’t talk about how assets will be divided or why certain decisions are made, even meaningful items like a lake house, farmland, or family heirlooms can become sources of disagreement. Alternatively, other families approach this more proactively through lifetime gifting, giving parents the chance to see their legacy at work while also potentially reducing their taxable estate.
No matter the path a family chooses, what makes a difference is open, intentional communication. Talking through plans ahead of time helps align expectations and gives families a chance to explain the reasoning behind their decisions. Just as important, it allows parents to pass down the values and thought processes that shaped their financial choices in the first place. In many ways, those conversations are just as valuable, and memorable, as the assets themselves.
Kids Learn About Money Long Before You Talk About It.
Another idea that stuck with me is how much children absorb simply by watching. Even when money isn’t openly discussed, kids are paying attention to spending habits, priorities, and even offhand comments.
Something as simple as saying, “We can’t afford that,” can leave a lasting impression. Over time, that kind of language may lead kids to associate money with limitation or anxiety. Shifting the message slightly to, “We’re choosing not to spend money on that so we can spend it on something else,” introduces a completely different mindset, one rooted in choice and prioritization.
Those small, everyday decisions add up. The way a family approaches dining out, vacations, shopping, or even minor purchases sends consistent signals about what matters. Kids internalize those patterns and often carry them into adulthood.
One practical takeaway from the webinar was to involve kids in these decisions when possible. If a child wants something, asking what they’re willing to give up to afford it can turn a simple request into a valuable lesson about trade-offs.
Generosity is another area where visibility matters. When giving happens quietly in the background, kids may not fully understand its importance. Finding ways to include them, whether that’s through structured systems like “give, save, spend” or family traditions around charitable giving, helps reinforce the idea that money is a tool, not just something to accumulate.
The Right Financial Tools Depend on the Bigger Picture of Your Goals.
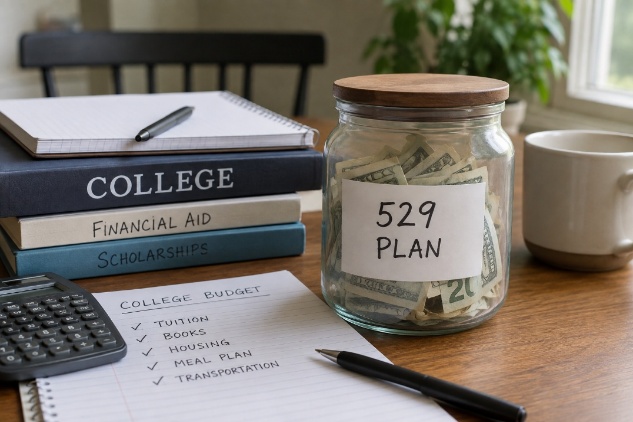
We also spent time discussing the different financial tools families can use, and one thing quickly became clear: There’s no shortage of options. Whether it’s 529 education plans, custodial accounts, newer Trump accounts, or trusts, each option comes with distinct benefits and considerations.
529 plans, for example, have become more flexible over time. They still offer some tax advantages, especially at the state level in Iowa, but can now be used for a wider range of education-related expenses than many people realize. There are also more options than there used to be if the funds don’t end up being used for a traditional college experience, including Roth IRA rollovers.
That said, not every family wants that level of spending restriction. Custodial accounts offer more flexibility in how funds can be used, but they also come with less control. Once a child reaches a certain age, the account becomes fully theirs to manage, which can be either empowering or concerning, depending on the situation.
Trusts offer a different kind of solution. They allow families to build in structure and guidance, especially if there are concerns about handing over a large sum of money too early. By setting parameters around how and when funds are distributed, parents can help ensure that the money supports long-term stability.
That was really the key takeaway: It’s less about choosing the “best” tool and more about choosing the right combination of tools for your specific goals and values. Consult a financial professional regarding your particular situation.
Closing Thoughts on Transferring Wealth and Values
What stood out most to me after this conversation was how intentional this process needs to be. Passing down wealth isn’t just about dividing assets; it’s about preparing the next generation to handle them thoughtfully. That preparation happens over time, through conversations, examples, and small teaching moments that build understanding and perspective. Whether you’re raising young kids, guiding teenagers, or thinking about how to support adult children, emphasize communication and consistency. And if there’s any reassurance in all of this, it’s that you don’t have to have everything figured out to get started. The most important step is simply beginning the conversation. At Foster Group, truly caring for our clients means taking the time to learn what’s in their hearts and helping them pursue their goals.